Crash Repair Cover
Pays toward fixing your car after a crash, whether another driver was involved or not.
Your car takes you to work, to school runs, and to the places that matter. I work as your insurance consultant, so you get straight advice on what to cover and no extras you will never use.
Get Your Quote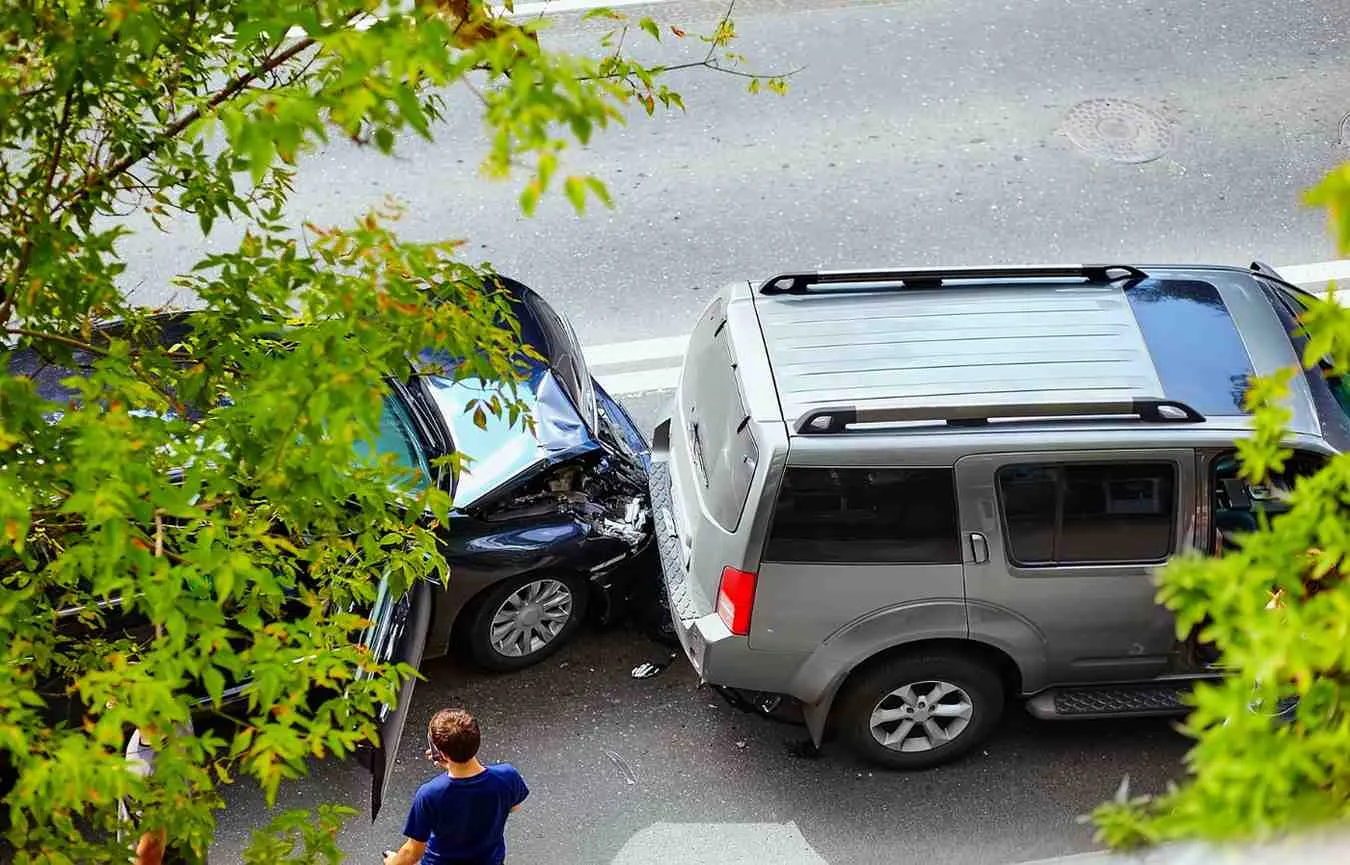
Choosing car insurance should not feel like signing a contract you cannot follow. I give you answers in normal words, so you know exactly what you are buying.
Every driver has a different story. My job as a consultant is to weigh how you drive, what your car is worth, and which repair bill would really hurt.
Each part of a car policy does a different job. Here is what matters for the way you drive.
Pays toward fixing your car after a crash, whether another driver was involved or not.
Covers damage or injury you cause to someone else, which is the part most drivers underbuy.
Handles hail dents, falling branches, smashed windows, and trouble that has nothing to do with driving.
Helps with hospital bills for you and your passengers, no matter who ends up at fault.
Gets you a tow, a jump start, or a loaner car so a bad morning does not turn into a lost week.
You hear what the car actually needs before any number comes up.
I recommend limits that suit your car and your savings, not a generic package.
When something happens, I walk you through the steps in order.
I point out exclusions early, while you can still change your mind.
I review safe driving, low miles, and multi car savings at every renewal.
New car, new address, new driver at home, I walk you through each change without long waits.
Your car, your usual mileage, and who else gets behind the wheel.
I show you what changes when limits go up or a deductible moves.
Paperwork gets reviewed line by line so nothing surprises you later.
Renewals get a fresh look instead of rolling over on autopilot.
Not always. On a clean record, one small claim often matters less than drivers expect. Fault, claim size, and timing carry the real weight.
Pick the highest amount you could hand over tomorrow without stress. A bigger deductible cuts your monthly cost, but only helps if the cash is really there.
It depends on what the car is worth now. Once the yearly cost creeps toward a tenth of that value, many drivers drop it and keep liability instead.
Rates usually climb, since new drivers have less road time. Listing them on the older car, good grades, and a driving course all soften the jump.
Get to a safe spot, check on everyone, then photograph both cars and the plates. Swap policy details, skip the fault debate, and report it the same day.
I paid for the same car coverage for years without knowing what half of it did. One short call later, I dropped one extra and raised the part that mattered.
Ruthie M. Sedan ownerAdding a sixteen year old to the car policy sounded rough on the budget. I learned which car to list him on and which discounts he qualified for, and the final number worked.
Dale K. Parent of a new driverSomeone backed into my truck in a parking lot and drove off. I called with no idea where to start, and had a checklist and a clear deductible answer that same afternoon.
Angie P. Pickup driver